Bitcoin swung more than four grand within hours of the August CPI print, and traders leaning short and long both got liquidated before the dust settled.
Bitcoin dropped first; that’s the part nobody remembers now. Then, somehow, it tacked on over four grand in a handful of hours. And then it handed back three thousand of that same move, more or less back to square one.
Anyone eyeballing the order book without context, honestly, would’ve guessed a hack, a whale dump, maybe some regulatory scare out of nowhere. Wasn’t any of that. Not even close.
The trigger, for what it’s worth, was Thursday’s inflation report. Annual CPI for August landed at 3.4 percent, which is basically what economists had already penciled in, straight off the Bureau of Labor Statistics’ own release. The monthly number, 0.4 percent, ran a touch hotter than the market wanted, and core inflation crept up to 2.4 percent annually.
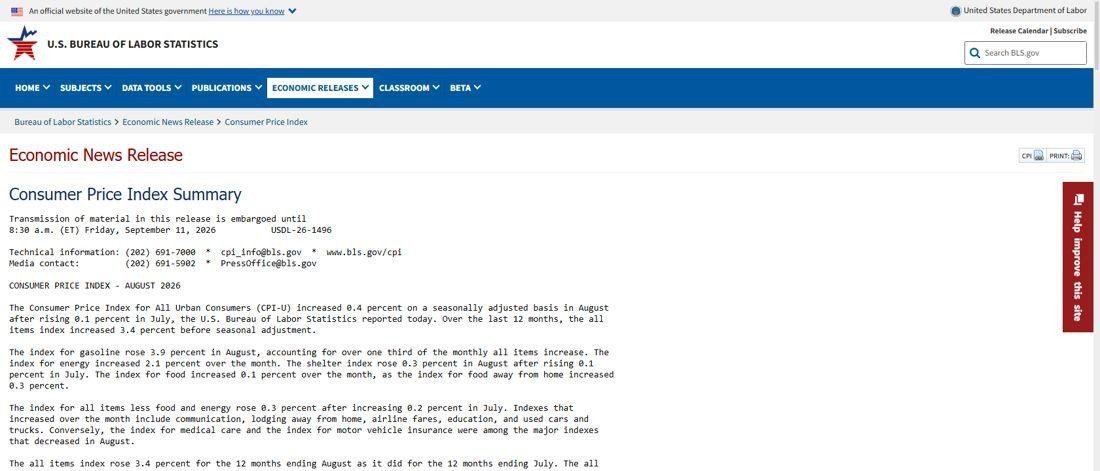
Source: U.S. Bureau of Labor Statistics, Consumer Price Index Summary, August 2026
Bitcoin had been drifting near 77,000 dollars going into it. The knee-jerk reaction sent it sliding toward roughly 76,500, which honestly is a pretty ordinary risk-off flinch on a day like this. What happened next wasn’t ordinary. Not even a little.
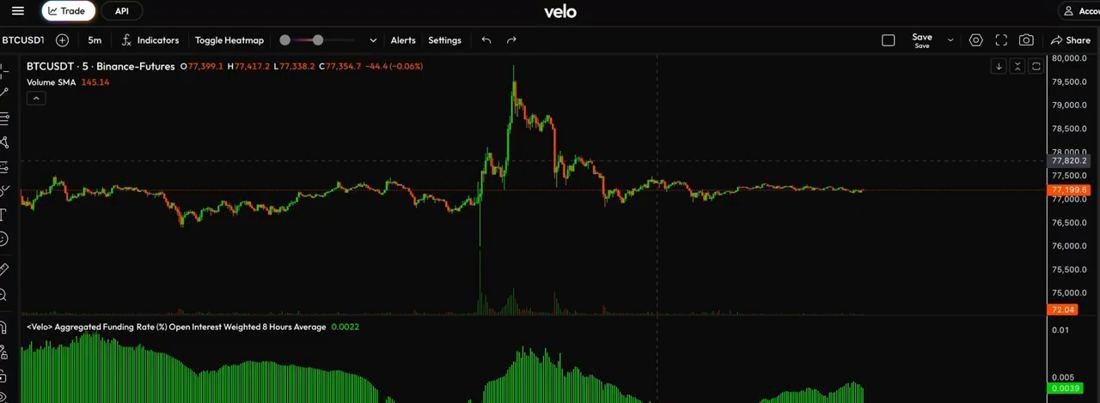
Source: Binance Futures BTC/USDT, 5-minute, via Velo
Within that same session, price tore back through 77,500 and spiked toward the 79,500 dollar area, visible right on the chart below. Then it slumped again. Same range. Both directions. All inside a handful of candles.
Charts from the hours before the release showed something worth noticing. Funding rates had drifted negative while open interest kept climbing. That’s usually a decent tell that short positions were piling up ahead of the number, betting a hot print would wreck the market.
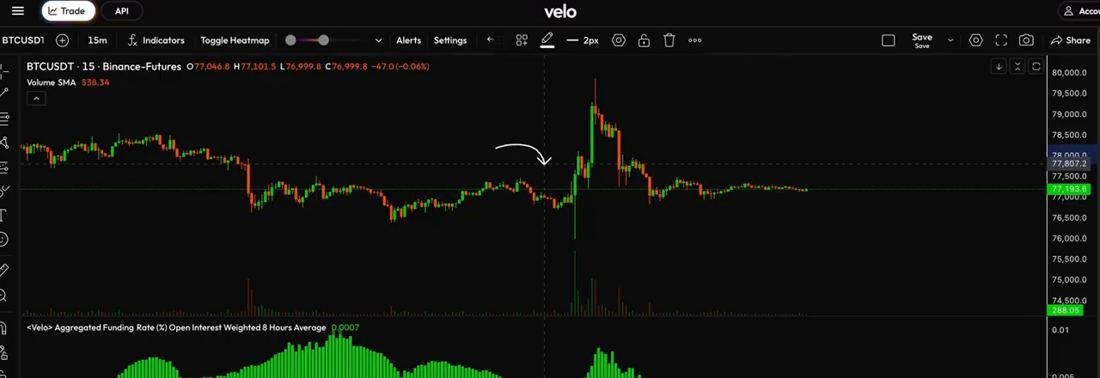
Source: Binance Futures BTC/USDT, 15-minute, via Velo
Price snapped higher instead, and those shorts got run over pretty fast. Funding flipped positive almost as quickly as it had gone negative. That’s the real, mechanical reason the bounce looked so violent, not some sudden wave of conviction buying. Mostly it was sellers getting forced out the door, then buyers who chased the top paid for it on the slide back down. Worth saying plainly, none of this is investment advice. Funding and open interest can flip within hours.
What actually makes this print matter is what’s coming next. The Federal Reserve’s own published calendar has its September meeting running the 15th and 16th, with the rate decision landing Wednesday afternoon.
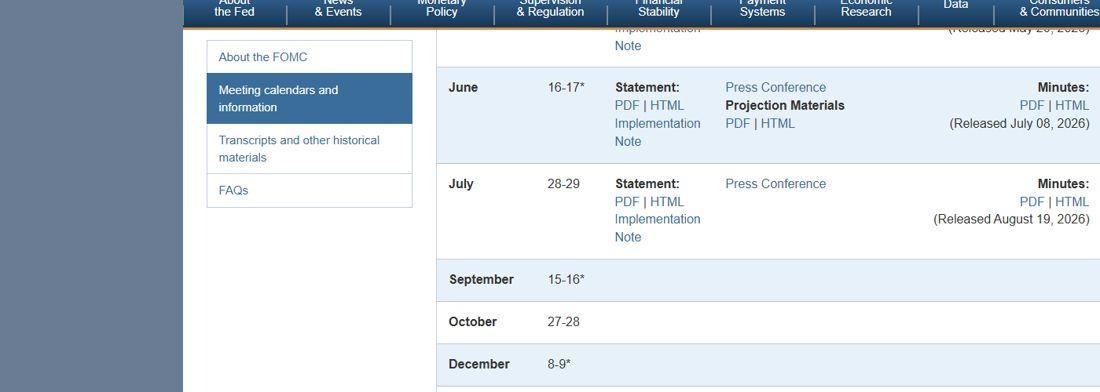
Source: Federal Reserve, FOMC meeting calendar
Odds of a hike had already been climbing before Thursday, and the CME FedWatch tool, which prices meeting odds off real interest rate futures, now shows an 87.3 percent probability of a quarter-point hike. A month ago that same probability sat at just 40.6 percent. A week ago it was already up to 59.4. The move has been fast.
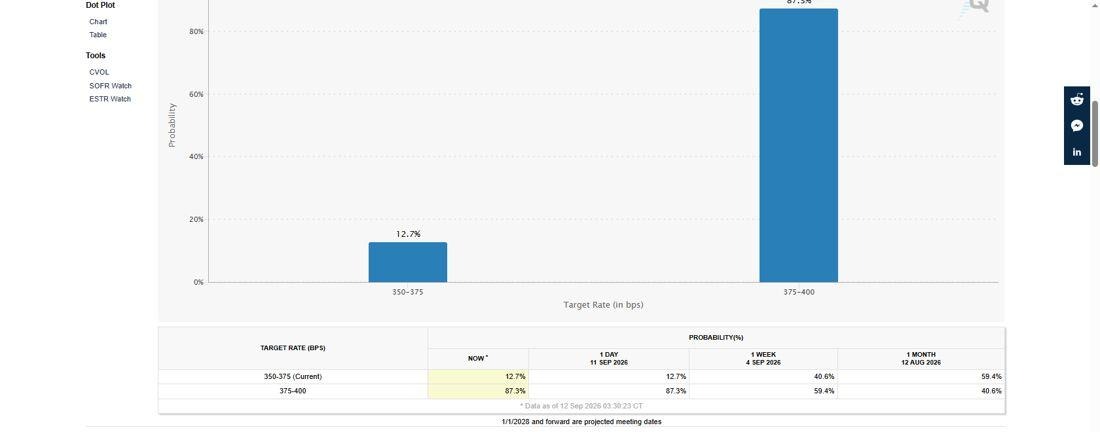
Source: CME FedWatch Tool, target rate probabilities
A hike, of course, is the opposite of what crypto bulls actually want here. Tighter policy usually means less liquidity floating around risk assets generally, and Bitcoin hasn’t exactly thrived historically when the Fed’s actively squeezing instead of easing.
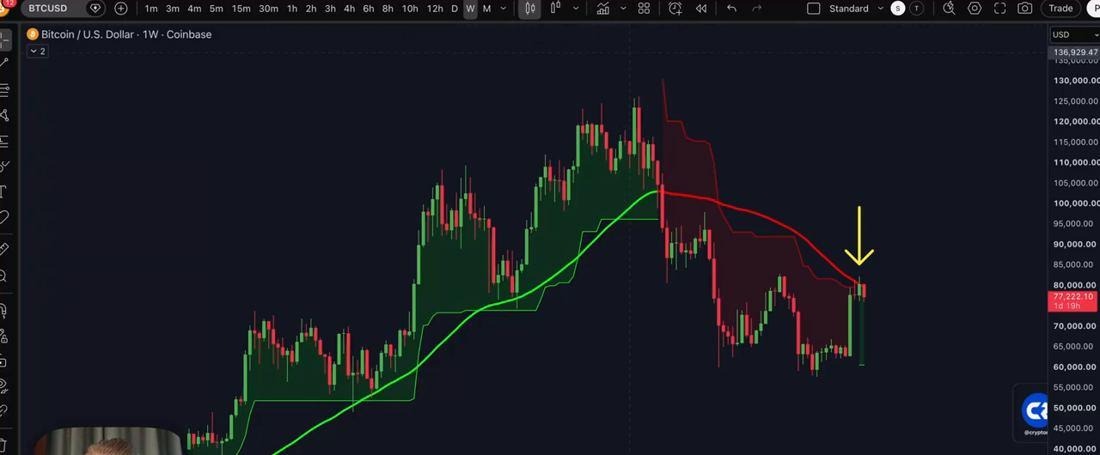
Zoom out to the weekly timeframe and, if anything, the picture gets less dramatic. Bitcoin’s still capped below its 50-week moving average, the same resistance line that’s rejected pretty much every real bounce attempt since price peaked up near the 130,000-dollar area.
Source: Bitcoin/USD, weekly, TradingView (Coinbase feed)
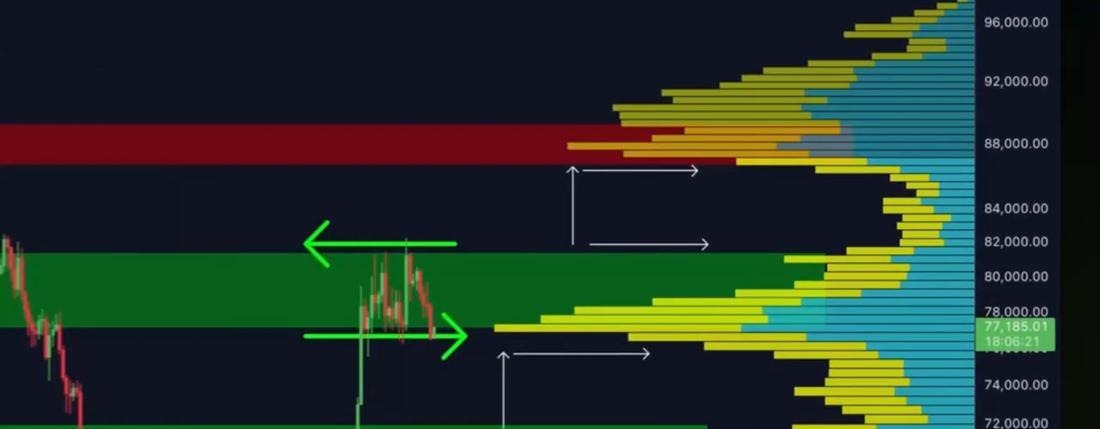
Liquidity maps built off open exchange order flow show a fairly thin band of resistance stacking above roughly 81,000 dollars, with support pretty much evaporating below about 72,000. Whichever side of that range breaks first is probably going to move fast, mostly because there just isn’t much standing in the way once it does.
Source: BTC liquidation heatmap, Binance Futures, via Velo
Nobody really knows which side that’ll be, least of all before Wednesday. More ongoing Bitcoin coverage sits on LiveBitcoinNews’ Bitcoin hub, if that’s useful.
Ether spiked toward roughly 2,700 dollars in that same window, testing the upper edge of a multi-month range on its weekly chart before slipping back. Call it a fakeout for now. Though, honestly, the broader structure on that timeframe still looks better than it did earlier this year.
Whether that turns into a real breakout or just another rejection probably comes down to the same four days everything else in this market is stuck waiting on.
The post Bitcoin’s CPI-Day Whipsaw Trapped Traders on Both Sides of the Trade appeared first on Live Bitcoin News.